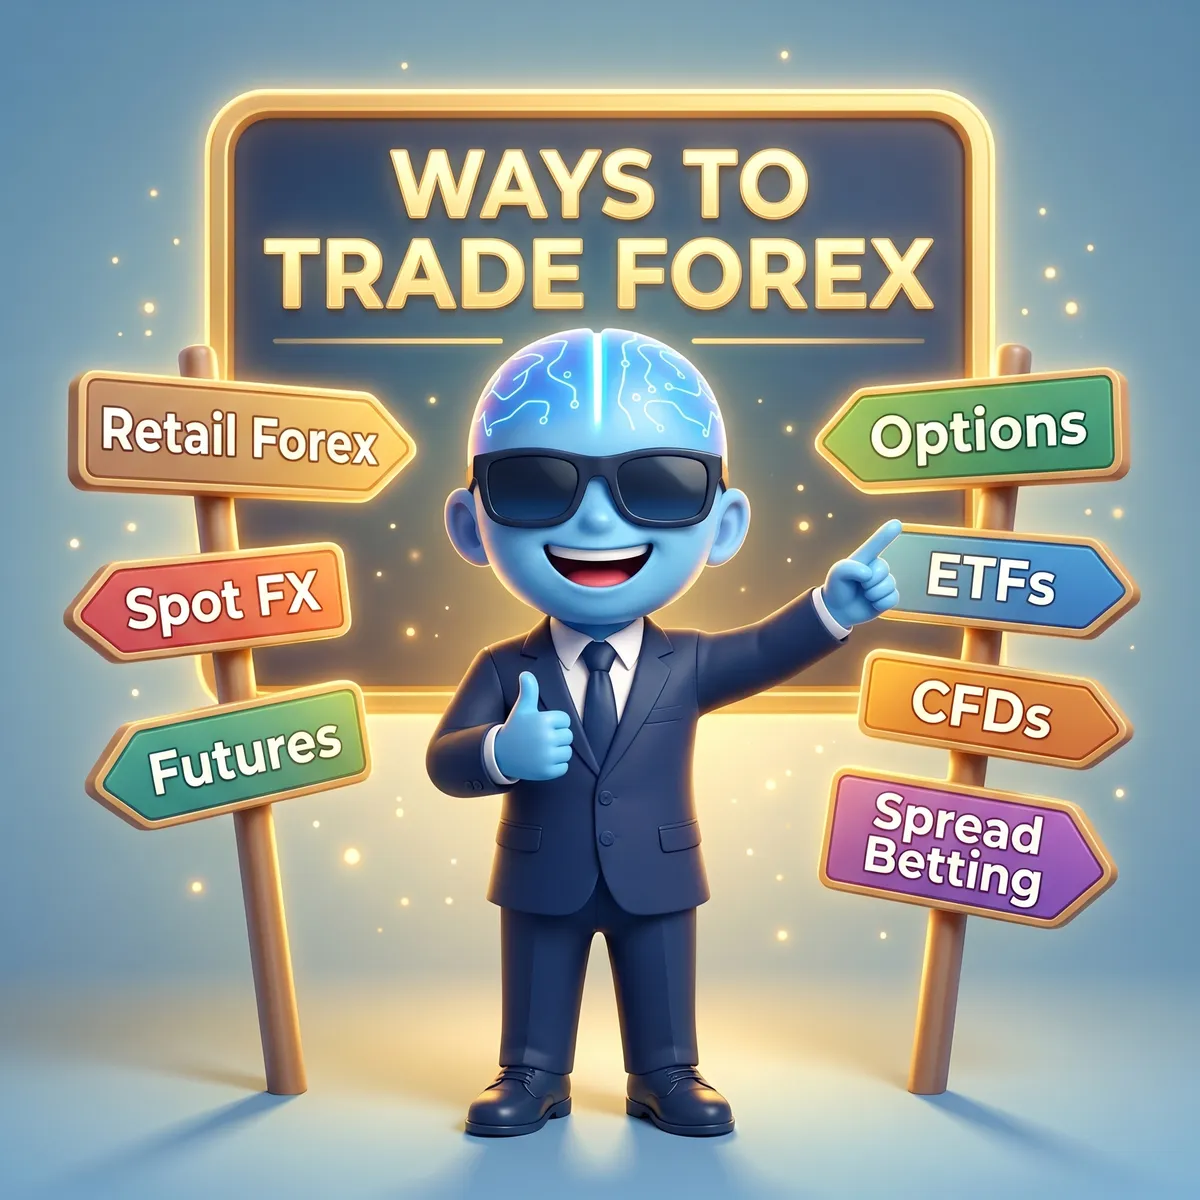
Ways to Trade Forex
Spot, retail forex, futures, options, ETFs, CFDs and spread bets
Read
Seven instruments open the door to the currency market — but as a retail trader you will only walk through two of them.
So how do you actually get a position on? The forex market has more than one entrance. Traders reach it through seven different instruments — and retail traders like us use just two of them. Let’s find the right door.
The most popular instruments are retail forex, spot FX, currency futures, currency options, currency exchange-traded funds (ETFs), forex CFDs, and forex spread bets.
Everything below is framed for the individual (“retail”) trader. Institutional-only instruments like FX swaps and forwards we’ll leave to the banks.
Currency Futures
A future is a contract to buy or sell an asset at a set price on a set future date (hence the name).
A currency future fixes the price at which a currency can be bought or sold and locks in a specific date for the exchange. The Chicago Mercantile Exchange (CME) created them back in 1972.
Because futures are standardized and traded on a centralized exchange, the market is transparent and well-regulated — price and transaction data are there for everyone to see.
Currency Options
An option gives the buyer the right — but not the obligation — to buy or sell an asset at a set price on or before the option’s expiration date.
Sell (or “write”) an option instead and you flip to the other side: now you are obliged to buy or sell at that price if the buyer exercises.
Like futures, currency options trade on exchanges such as the Chicago Mercantile Exchange (CME), the International Securities Exchange (ISE), and the Philadelphia Stock Exchange (PHLX).
The catch: FX option hours are limited for some contracts, and liquidity is nowhere near as deep as the futures or spot market.
Currency ETFs
A currency ETF gives you exposure to a single currency or a basket of them through a managed fund — no need to place individual trades.
You can use one to speculate on a currency, diversify a portfolio, or hedge currency risk. Financial institutions buy and hold the currencies in a fund, then sell you shares of that fund on an exchange, so you trade them just like a stock.
Same limitation as options: the market isn’t open 24 hours, and ETFs carry trading commissions and other costs.
A round-turn is one complete trade — opening a position and then closing it. Costs like commissions and the spread are usually quoted per round-turn, not per click.
Spot FX
The spot FX market is an off-exchange, or over-the-counter (OTC), market. There is no central trading floor — a customer trades directly with a counterparty, and the whole thing runs 24 hours a day.
The primary market is the interdealer (or interbank) market, where FX dealers trade with each other. It is only open to institutions that trade in huge size — banks, insurers, pension funds, large corporations.
In spot FX you are not trading the currencies themselves — you are trading a contract to make or take delivery of a currency. Buy EUR/USD on the spot market and you hold a binding agreement to receive euros for U.S. dollars at the current exchange rate.
And despite the name, spot trades don’t settle “on the spot”. Settlement usually lands two business days after the trade — known as T+2 (some pairs, like USD/CAD, settle at T+1).
The real spot FX market is institutional. Retail traders reach forex through a secondary market built on top of it — that’s next.
Retail Forex
A secondary OTC market is where retail traders get in. Access comes through forex trading providers, who trade the primary market on your behalf, find the best available price, then add a markup — exactly like a shop buying wholesale and selling at retail.
Forex trading providers are usually called “forex brokers”, but technically they are not brokers. A broker is a neutral middleman between a buyer and a seller. Your forex provider is your counterparty — if you buy, it sells to you; if you sell, it buys from you. We’ll keep calling it a “broker” because everyone does, but it pays to know the difference.
A spot forex contract normally requires delivery within two days — but in retail forex, nobody ever takes delivery. And it’s not just a contract, it’s a leveraged contract.
Leverage lets you control a large position with a small deposit. Retail brokers let you open positions worth up to 50 times your required margin.
So with $2,000, you can open a EUR/USD trade worth $100,000.
The same 50× leverage that lets $2,000 control $100,000 also magnifies losses. A move of just 2% against a $100,000 position is a $2,000 loss — your entire margin. Leverage increases your risk exactly as much as your potential profit. Never trade leverage you don’t understand.
In the U.S., the CFTC caps major-pair leverage at 50:1. In the EU and UK, ESMA and the FCA cap it tighter, at 30:1. Lower caps mean smaller positions per dollar of margin — and less risk.
You never actually have to deliver $100,000 of euros. You close out a retail forex trade by making an equal but opposite trade — bought pounds with dollars? Sell pounds for dollars to close. (Also called offsetting or liquidating.)
Leave a position open at the end of the trading day and your broker automatically rolls it over to the next value date, so you never take delivery. This roll is called Tomorrow-Next, or Tom-Next, and it repeats indefinitely until you close.
Each roll either charges or pays you a swap (or rollover) fee, which your broker debits or credits to your account balance.
Retail forex is speculative: traders are betting on which way exchange rates move, not looking to take home a pile of foreign banknotes.
Size is how big your position is. “Putting on size” or “sizing up” means trading larger — which, with leverage, also means putting more at risk.
Forex Spread Bet
A forex spread bet lets you speculate on which way a currency pair will move. It’s a derivative — you never own the underlying currency, you just bet on the direction.
Your profit or loss depends on how far the market moves in your favor and how much you bet per “point” of price movement. The price is derived from the pair’s price on the spot FX market.
One catch: if you live in the U.S., spread betting is illegal. It’s regulated in the U.K. by the FCA, but the U.S. treats it as internet gambling, which is currently forbidden.
Forex CFD
A contract for difference (CFD) is another derivative. Its price is derived from an underlying asset, and it pays out the difference in that asset’s value between when you open and close the trade.
A forex CFD is an agreement to exchange the difference in a currency pair’s price from open to close. You can trade it in both directions — take a long position if you think it rises, or a short position if you think it falls. Move your way, you profit; move against you, you lose.
In the EU and UK, regulators class a “rolling spot FX contract” as a CFD, precisely because there is never any intention to take delivery — the point is purely to speculate on price. (In the U.S., where CFDs are illegal, the same thing is called a retail forex transaction.)
Outside the U.S., retail forex is usually traded as CFDs or spread bets.
Futures, options, and ETFs are exchange-traded and transparent, but not open 24 hours. Spot FX is a 24-hour OTC market, but institutional. Retail traders reach forex through a leveraged secondary market — CFDs or spread bets — where leverage magnifies losses as much as gains.
See you on the desk. — AI Mentor