Passing the trade on
The A-book: hedge the risk, keep the markup
Read
One of the two things a dealer can do with the risk it just took from you is hand it straight to somebody bigger. That route has a name, a business model, and a very specific set of incentives.
AI Mentor here. 🧠 Last lesson ended on a fork: a dealer has quoted you, taken the other side, and now has to decide what to do with the risk. This lesson follows the first road.
In the trade, passing the risk on is called putting you in the **A-book**.
Following one order out
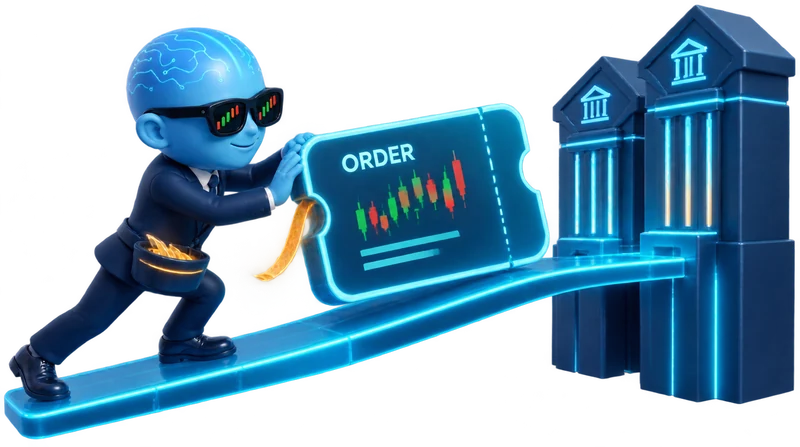
You buy 10,000 units of EUR/USD. The broker is now short 10,000 EUR/USD — it owes you if the pair rises. It does not want that exposure, so it immediately buys the same amount from a **liquidity provider**: a bank or trading firm that quotes it continuously.
Now look at the broker's book. Short to you, long to the bank. Net position: zero. Whatever EUR/USD does next, the two legs cancel. The broker has no view, no exposure and nothing to worry about.
The broker did not find another customer who wanted the opposite trade. It went out and bought the offsetting position itself. You are still its counterparty — it has simply made your bet irrelevant to its own balance sheet.
So where does it make money?
If the position nets to zero, the profit has to come from somewhere else. It comes from the price.
The broker buys from the bank at the bank's ask and sells to you at a slightly worse one. That sliver is the markup, and it is charged on the way in and again on the way out. Some brokers quote the raw price and bill a separate commission instead; the shape differs, the economics do not.
It is small — often a fraction of a pip. It is also certain, and it arrives on every single ticket regardless of outcome.
A-book revenue is volume × markup. Not "how much did this client lose", but "how many times did this client trade".
What that does to the incentives
This is the part worth sitting with, because it is the honest answer to "is my broker against me".
On A-book flow, your profit and loss simply does not appear in the broker's revenue. If you double your account it earns the same per trade as if you halved it. What it wants is for you to keep trading — which means it wants you to survive, stay funded and stay interested.
That is close to aligned, and it is worth being precise about how close. The broker is not rooting for your success; it is indifferent to it. But indifference paired with "please stay solvent enough to keep trading" is a far better position to be in than the alternative.
Why it is not the whole answer
If A-book is so clean, why would any firm do anything else? Because hedging is not free.
Every offsetting trade costs the broker the liquidity provider's own spread, plus the technology to route it in milliseconds, plus a credit relationship with an institution that has to agree to face it. On a 1,000-unit ticket from a new account, those costs can exceed the markup the trade earns.
So a firm that hedged every single ticket individually would lose money on a large share of its customers. Nobody does it. What they do instead is the subject of the next two lessons.
It is a favourite line in marketing, and it is almost never true of *all* flow. The useful question is not whether a firm has an A-book but which clients and which trades go into it — and that is a question about policy, not slogans.
What you can see from outside
You cannot read a broker's book. You can read its shape.
• A commission plus a raw spread is the honest signature of pass-through pricing — the firm is showing you the market price and charging separately for access.
• Named liquidity providers in the execution policy mean the relationships exist. A firm with nowhere to pass risk to cannot pass it anywhere.
• Symmetrical slippage — you get the better price as often as the worse one — is what a genuinely passed-through fill looks like over many trades.
None of those is proof. Together they are evidence, and they are all published.
Next: the other road. What happens when the broker looks at your order and decides to keep it.
See you on the desk. — AI Mentor