Who is on the other side?
Exchange or dealer — the fact that decides everything else
Read
Every trade needs somebody taking the opposite view. Who that somebody is — another trader, or the broker itself — changes what your order costs, what price you get, and whose interests it serves.
AI Mentor here. 🧠 You have spent nine islands learning what to trade and when. This one is about who you are trading with — and it is the part almost nobody checks before they fund an account.
Here is the question the whole island turns on. You press Buy. Somewhere, something has to sell. Who?
Two completely different machines
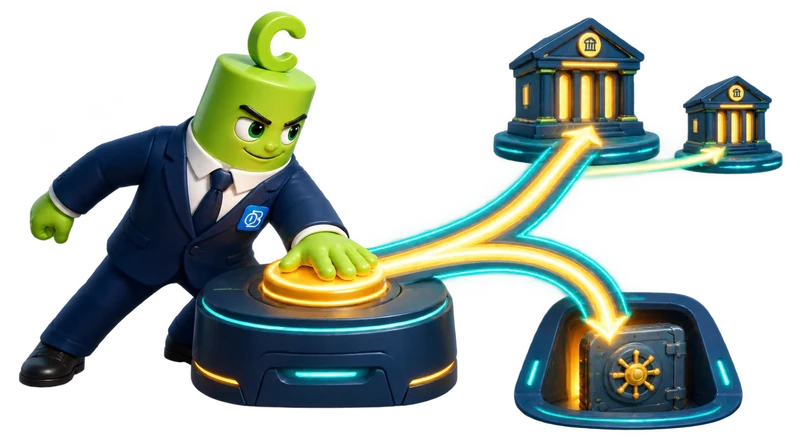
There are two ways a market can be built, and almost every argument about brokers comes down to which one you are standing in.
An exchange is a meeting place. Buyers and sellers post what they will do, the exchange matches them, and it takes a fee for keeping the venue. It does not care which way price goes. It has no position.
A dealer is a shop. You do not meet another customer — you trade with the shop itself. It quotes you a price to buy and a price to sell, and it makes its living on the difference between them. It absolutely has a position, because it just took the other half of yours.
Does this firm match me with someone else, or become the someone else? Everything in this island — pricing, spread, slippage, conflicts — follows from the answer.
What you are actually holding
This is where it gets concrete, and where a lot of new traders are quietly wrong.
If you buy a share of a company through a broker that routes to an exchange, you end up owning the share. It exists. It sits in a depository with your name attached, it pays you dividends, and it survives your broker going out of business.
If you "buy EUR/USD" at a retail forex or CFD broker, you have not bought any euros. There are no euros. What you have is a contract with that firm which says: if EUR/USD goes up, they owe you the difference; if it goes down, you owe them.
That is not a scandal, and it is not hidden — it is written on the front page of the product disclosure. But it has one consequence worth sitting with: the value of your position depends on the firm being able to pay. A share does not care whether your broker survives. A contract for difference is only as good as the counterparty behind it.
When the broker is your counterparty, "is this firm solvent and supervised" is not a box-ticking question — it is the question of whether your profit is collectable. Segregated client money and a real regulator exist precisely for this.
Why dealers exist at all
The obvious reaction is: fine, I will just use an exchange. For most currency traders, that option does not exist.
There is no central exchange for spot foreign exchange. It is an over-the-counter market — a web of banks and institutions quoting each other directly — and the sums it deals in are not retail-sized. The smallest unit that moves comfortably between banks is far larger than a private account would ever trade.
A dealer solves that by standing in the middle. It takes the institutional market on one side and slices it into positions small enough for you on the other. Trading 1,000 units of a currency pair is possible because a firm is willing to write you a contract for it, not because a bank somewhere accepted a 1,000-unit order.
So the dealer is doing something genuinely useful. It is also, unavoidably, on the other side of you. Both of those are true at once, and holding both is the whole skill this island teaches.
Where the conflict actually sits
Take the crude version first, because you will hear it everywhere: "your broker wants you to lose."
It is too simple, and being too simple makes it useless. A dealer that has taken the other side of your trade has a choice about what to do next, and that choice — not the fact that it quoted you — is what decides whether your interests are aligned.
It can pass the risk on to somebody bigger and earn a small, certain margin on your volume. It can keep the risk and earn — or lose — whatever you lose or earn. Real firms do both, on different flow, for reasons that are mostly about risk management rather than villainy.
Those two routes have names, they are the subject of the next two lessons, and you cannot evaluate a broker without knowing which one your orders are travelling.
A broker is not good or bad because it takes the other side. It is good or bad because of what it does with the risk afterwards, and how honestly it tells you.
How to check, in ninety seconds
You can place any firm on this map without reading a single review.
• Read the instrument, not the marketing. "Shares" and "share CFDs" are different products with similar names. The disclosure says which.
• Find the entity. The name on the website is a brand; the name on the client agreement is who owes you money. They are not always in the same country.
• Find the venue. A broker that routes to an exchange will name it. A dealer will describe itself as the counterparty, or as dealing "on own account".
Three questions, all answerable from documents the firm has to publish. We will come back to those documents properly at the end of the island.
Next we follow a single order out of the trading app and watch where it goes when the dealer decides to pass it on.
See you on the desk. — AI Mentor