What is a Spread?
The hidden cost built into every forex quote
Read
Every forex quote hides a toll — the gap between two prices that you pay before the trade even moves.
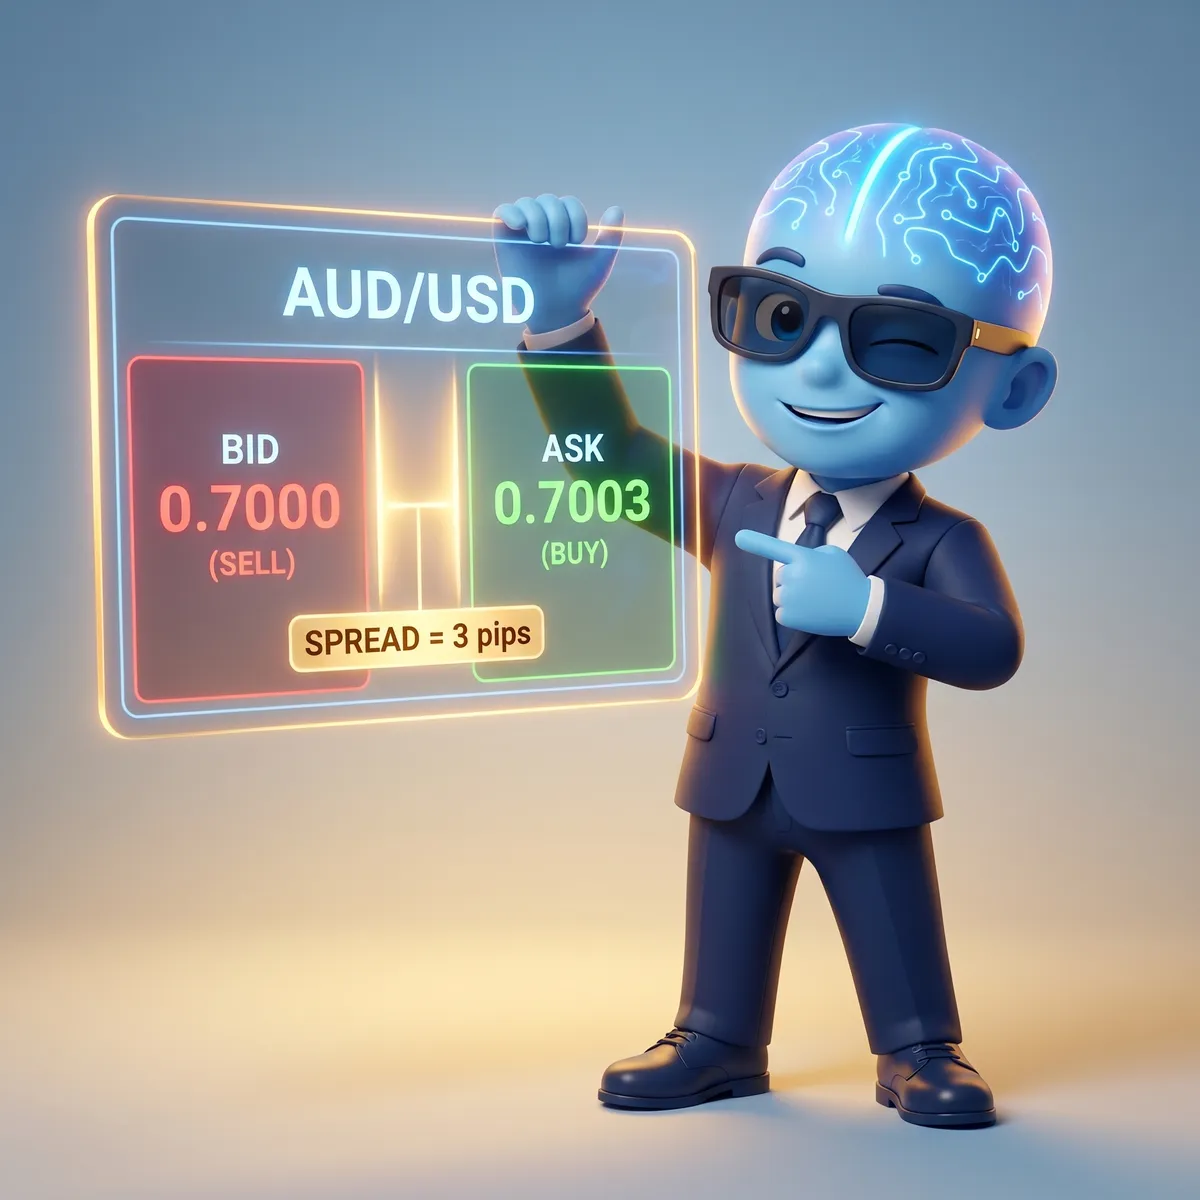
A broker never shows you one price. It shows you two: the bid, where you sell, and the ask, where you buy. The difference between them is the spread — and it is the cost of doing business on every single trade you place.
• The bid is the price at which you can SELL the base currency.
• The ask is the price at which you can BUY the base currency.
• The gap between them is the spread — also called the bid/ask spread.
Traders call the spread the toll — what you pay to cross the market. Tighter toll = cheaper trading.
How “no commission” brokers earn
The spread is how “no commission” brokers make their money.
It’s the fee for transaction immediacy — which is why traders use “transaction cost” and “bid-ask spread” to mean the same thing. Instead of charging a separate fee, the cost is built into the buy and sell price of the pair.
The broker sells the currency to you for a little more than it paid, and buys it from you for a little less than it can sell it for. That difference is the spread.
You already met the used-iPhone dealer in the Bid & Ask lesson — buy low at the bid, sell high at the ask, keep the gap. Your broker runs the exact same book.
When a broker claims “no commission,” it’s misleading. There’s no separate fee, but you still pay a commission — it’s just baked into the bid/ask spread on every trade.
How the spread is measured
The spread is usually measured in pips — the smallest unit of a currency pair’s price movement.
For most pairs, one pip is 0.0001. A 2-pip spread on EUR/USD looks like 1.1051 / 1.1053.
Pairs involving the Japanese yen are quoted to only 2 decimals, so a USD/JPY quote of 110.00 / 110.04 shows a spread of 4 pips.
Fixed vs variable spreads
The spreads you see on a platform depend on the broker and how it makes money. There are two kinds:
1. Fixed — set by the broker, unchanging.
2. Variable (also called “floating”) — moves with the market.
Fixed spreads come from market-maker (“dealing desk”) brokers, who act as the counterparty to your trades. Variable spreads come from non-dealing desk brokers, who pass through prices from several liquidity providers.
Fixed = predictable cost from a single price source, but you can get requoted. Variable = tighter when the market is calm, wider when it’s wild — and no requotes.
Fixed spreads
Fixed spreads stay the same no matter the market. Whether it’s roaring or dead quiet, the spread doesn’t move.
A dealing desk can hold them steady because it controls the prices it shows you: it buys large positions from its liquidity providers and offers them to traders in smaller sizes, acting as the counterparty to every trade.
The upside: smaller capital requirements and predictable costs. Since the spread never changes, you always know exactly what you’ll pay to open a trade — handy for a smaller account.
The catch — requotes. Pricing comes from a single source (your broker). When the market moves fast, a fixed spread can’t stretch to keep up, so the broker blocks your order and asks you to accept a new price — almost always a worse one.
Slippage is the other catch: when prices are moving fast, the fill you actually get can land at a very different price from the one you clicked.
Variable spreads
Variable spreads are always changing. The gap between the bid and ask floats with supply, demand, and overall market volatility.
Non-dealing desk brokers source pricing from multiple liquidity providers and pass it straight through, so they have no control over the spread — it widens or tightens with the market.
Spreads typically widen during economic data releases and any time liquidity thins out, such as holidays or the quiet gaps between trading sessions.
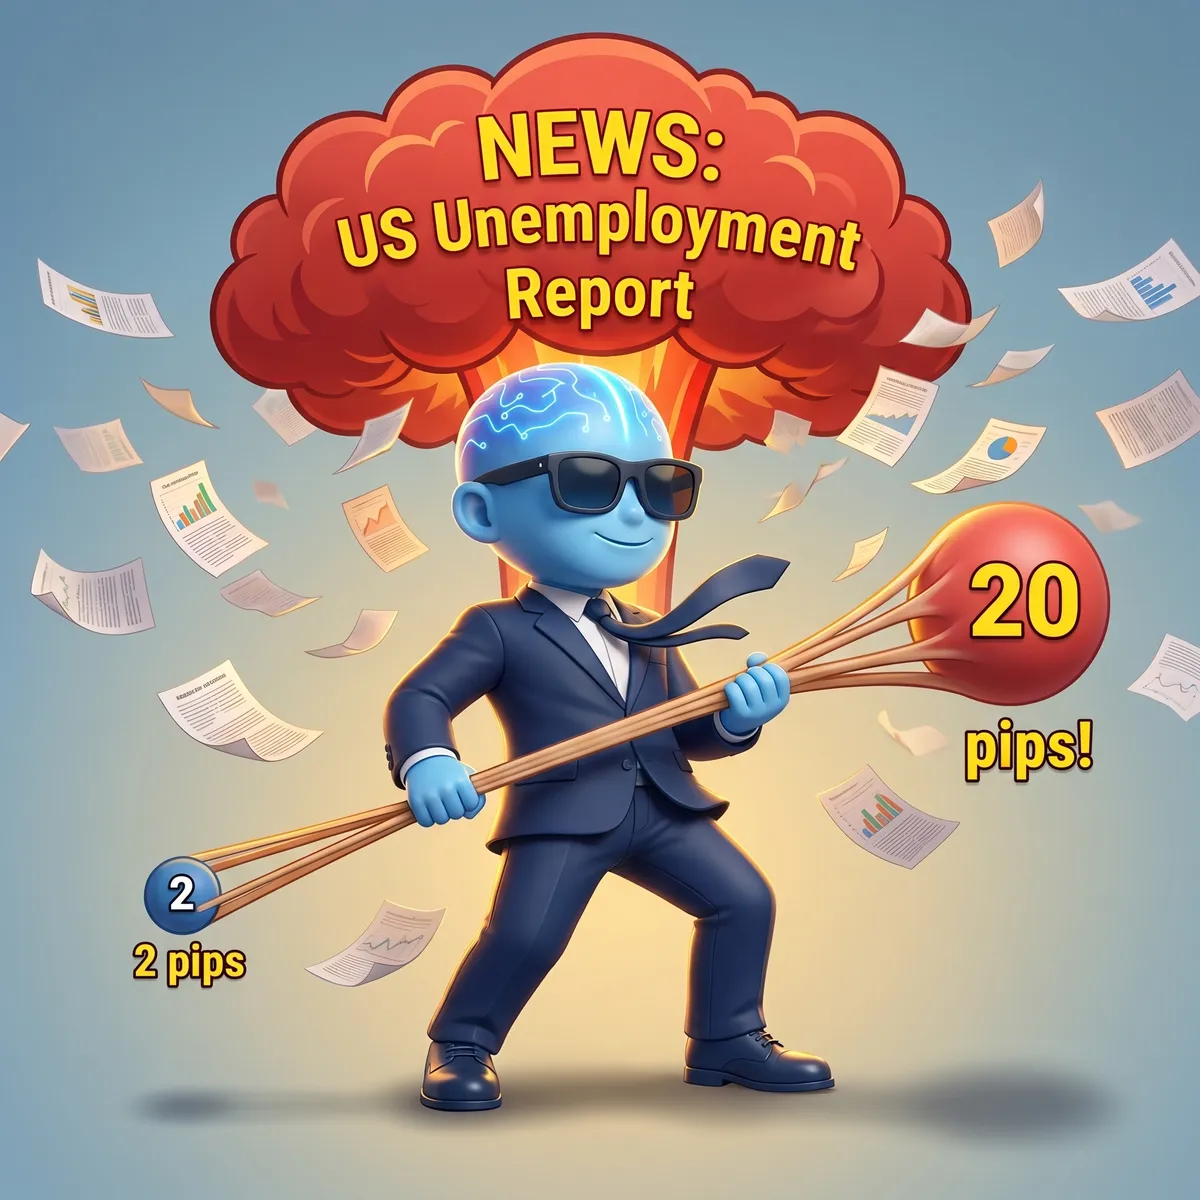
Say you’re about to buy EUR/USD on a 2-pip spread. The U.S. jobs report drops, and the spread snaps out to 20 pips before you can click.
Spreads can also jolt wider on a surprise political headline or an off-hours central-bank comment about a currency.
The upside: no requotes — the moving spread already prices in the market. Pricing is more transparent too, and competing liquidity providers often mean a tighter quote when the market is calm.
The catch: wide spreads hurt anyone trading fast or often. A spread that balloons on news can turn a profitable trade into an unprofitable one in the blink of an eye.
Which should you use?
It depends on how you trade.
Smaller accounts trading less often tend to do better on fixed spreads — predictable costs and low capital requirements.
Larger accounts trading frequently during peak hours, when spreads are tightest, usually prefer variable spreads — tighter pricing and no requotes.
Spread = your transaction cost
Here’s the part that actually hits your account. To turn a spread into a dollar cost, you need just two things:
1. The value per pip
2. The number of lots you’re trading
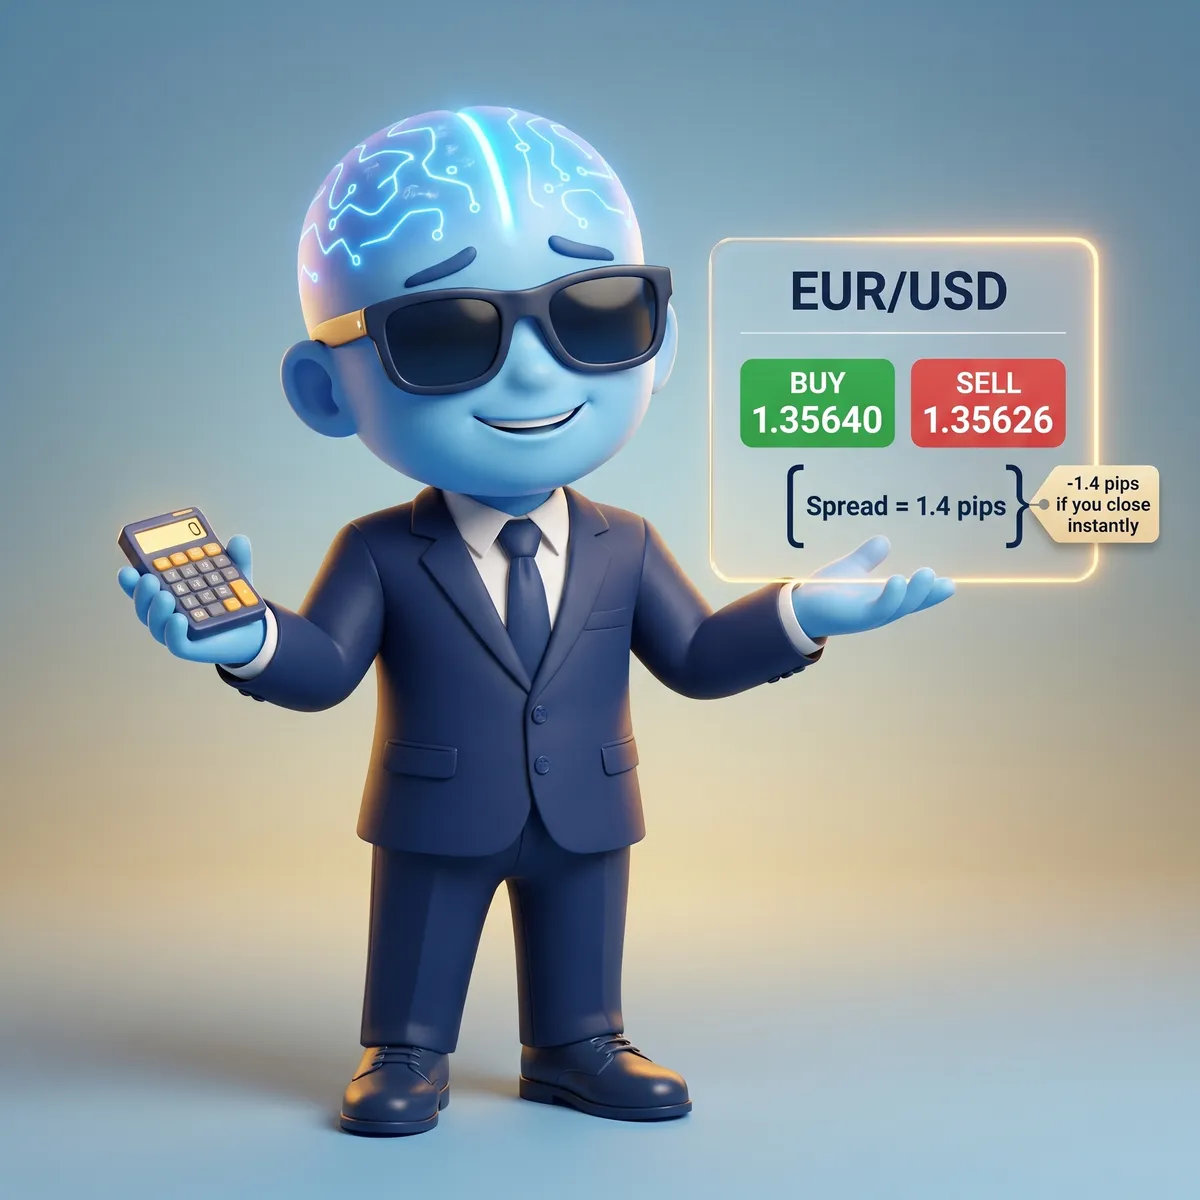
Take a EUR/USD quote where you can buy at 1.08640 and sell at 1.08626. Buy and immediately close, and you’re down 1.4 pips — that’s the spread.
Trading mini lots (10,000 units), the value per pip is $1, so that round-turn costs you $1.40 to open.
The cost is linear — multiply the cost per pip by the number of lots. Bigger position, bigger toll: trade 5 mini lots and that spread now costs $7.00.
You pay the toll on the round-turn — one full trade, open and close. That’s why a wide spread on a pair you trade often quietly adds up.
The spread is the gap between the bid (sell) and ask (buy) — the broker’s fee, baked into the price. It’s measured in pips: 1.1051 / 1.1053 is 2 pips. Cost = value per pip × lots, and it scales linearly, so know your toll before you click.
See you on the desk. — AI Mentor