Expiration, exercise & assignment
What happens on the deadline
Read
Every option carries a countdown. This is the lesson about the moment the clock hits zero — and the three very different things that can happen next.
Options don’t last forever. Each one has an expiration date stamped on it — a deadline after which it simply stops existing. And on that day, three words decide your fate: expire, exercise, or assign.
They sound like courtroom jargon, but they’re dead simple once you see who’s on each side. Two of them are just names for the same event seen from opposite ends of the trade.
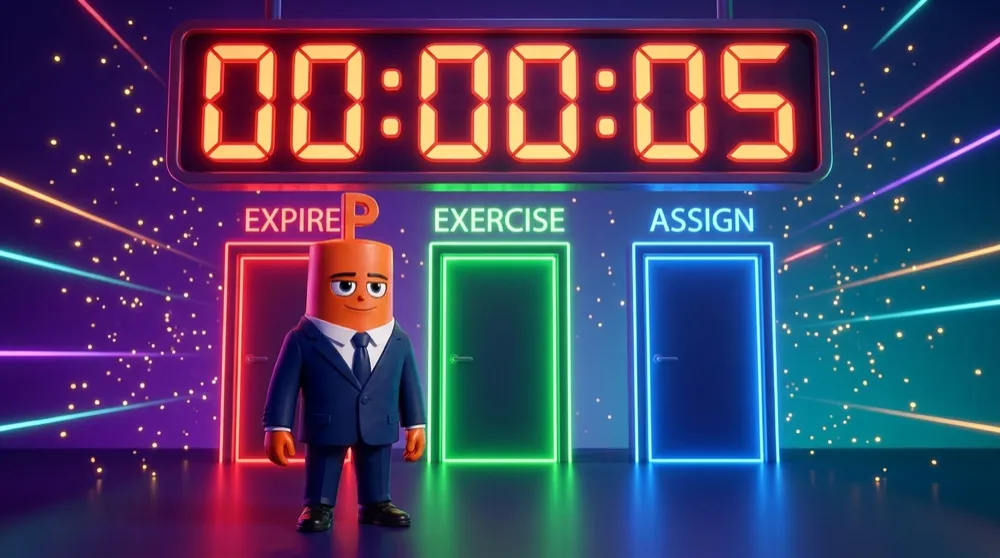
What decides which door you walk through? One thing: moneyness at the close — whether the option is in the money or out of the money when the bell rings. Let’s line up all three outcomes.
The three outcomes
Expire worthless. If your option is out of the money at expiration, it dies quietly. There’s no reason to use a right that’s worse than the open market, so it vanishes. The good news for a buyer: your loss is capped at the premium you paid — not a penny more.
Exercise. If the option is in the money, the buyer can use their right — actually buying or selling the 100 shares at the strike. That’s exercising: cashing in the deal the contract promised.
Assignment. Every exercised contract has a seller on the other end who gets assigned — forced to fulfill it. If a call gets exercised, the assigned seller must hand over 100 shares. If a put gets exercised, they must buy 100 shares. Same event, opposite seat.
Buyers exercise. Sellers get assigned. It’s a single handshake described from both sides — one person chooses to use the right, the other is obligated to honor it.
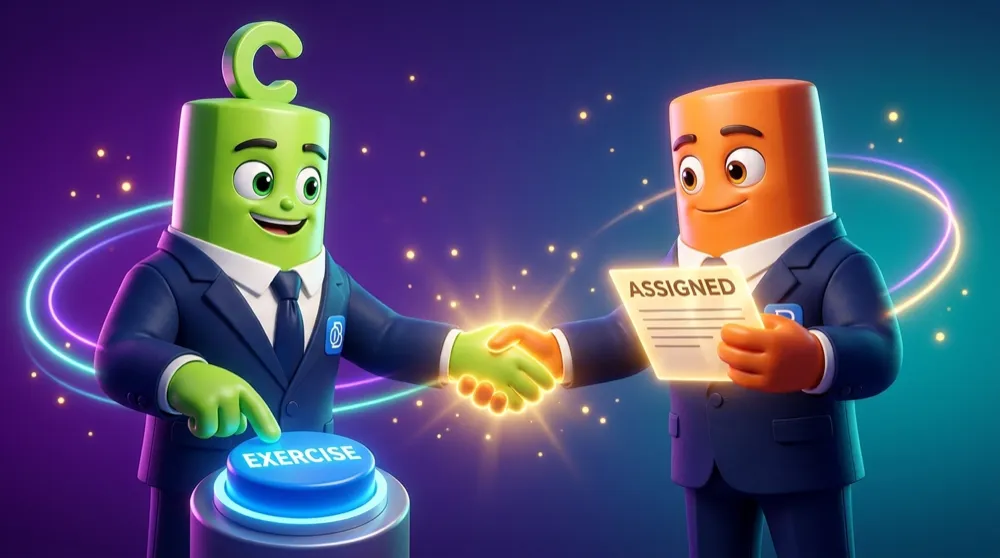
Buyers exercise. Sellers get assigned. Same event, two sides of the same trade.
Here’s the sting for sellers: assignment is not optional. Sell an in-the-money put and you can be forced to buy 100 shares at the strike, even if the stock has cratered. That obligation is exactly why selling options carries risk a buyer never faces.
The move almost everyone actually makes
Here’s the twist that surprises beginners: most traders never exercise at all. Buying or selling 100 real shares ties up a lot of cash, and it throws away any value the option has left. So instead, they just sell the option to close before expiration and pocket the difference.
Why is selling to close the smarter default? Because an in-the-money option is worth its intrinsic value plus whatever time value remains. Exercise it and you capture only the intrinsic part — the time value evaporates. Sell it and you keep both. You’re leaving money on the table by exercising early.
Won on your trade? Don’t exercise — sell to close and take the cash, time value and all. Only ever let an option expire when it’s worthless anyway. Exercising is the rare exception, not the plan.
The clock speeds up at the end
One last thing to respect about expiration: time value doesn’t drain evenly. As the deadline nears, it melts faster and faster — and in the final week it can fall off a cliff. Traders call this decay theta, and it accelerates the closer you get to zero.
Picture an ice cube on a warm day: slow to start, then a puddle before you know it. An out-of-the-money option running low on time is that puddle — its “maybe it’ll work out” is quietly running out, and its price bleeds down with it.
Time is the option buyer’s enemy and the seller’s friend. Every day that passes, a little value drips away from the buyer and toward the seller — whether the stock moves or not.
And that’s the mechanics chapter done. Expire, exercise, assign — plus the clock that never stops ticking. You’ve just graduated Elementary. Next up: the Greeks, where that ticking clock finally gets a number. 🏆