Trading earnings
The scheduled storm every quarter
Read
Four times a year a company opens its books and the stock can gap wildly overnight. The move is a mystery — but the date is on the calendar. Here is how to trade around the storm.
Most market surprises ambush you out of nowhere. Earnings are the rare exception: a violent, unpredictable move that arrives at a time you can circle weeks in advance. The company reports, the number lands, and the stock leaps or plunges before the next bell.
That mix — random direction, scheduled timing — makes earnings the single most misunderstood event in options. Beginners see a known date and think “easy money.” The pros see a trap dressed up as an opportunity. Let us find out why.
The balloon inflates before the report
Because everyone knows a big move is coming, option prices swell in the days before earnings. That swelling has a name: implied volatility, or IV. It is the market pricing in fear and hope — and it makes options expensive precisely when the crowd is most desperate to buy them.
Think of it like umbrella prices the hour before a downpour. Everyone wants one, so the corner shop jacks up the price. You are not paying for a better umbrella — you are paying for the panic.
You are not just betting on direction. You are betting the stock moves further than the already-inflated price implies. Pay full retail for the umbrella and you need a monsoon just to break even.
IV crush: the air leaves the balloon
The instant the report goes public, the uncertainty evaporates — the number is now a fact, not a guess. Implied volatility collapses in a heartbeat, and every option deflates with it. This is the IV crush, and it is the cruellest lesson in the Arena.
Here is the heartbreak: you can buy a call, be completely right that the stock rises, and still lose money. The volatility you overpaid for vanished overnight, and it drained your option faster than the stock move refilled it. Right on direction, wrong on the bet — a win that still lost.
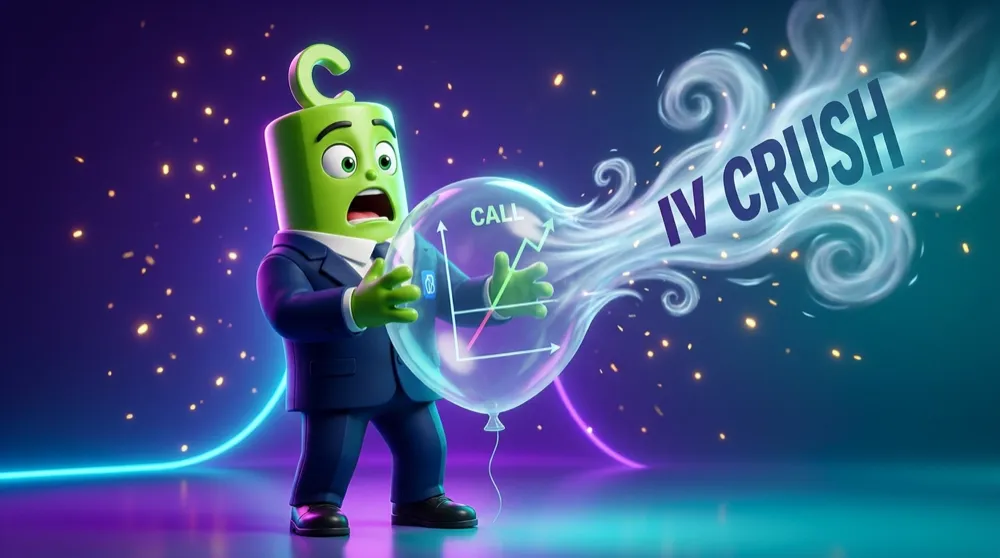
Being right about the direction and still losing money — that is the earnings heartbreak nobody warns you about.
The expected move: read the crowd’s guess
Option prices quietly whisper how big a swing the market is bracing for. It is called the expected move, and you can read it in seconds. Add the price of the at-the-money call and the at-the-money put that expire just after the report. That total is roughly how far the stock is expected to travel — up or down.
A quick example: a $100 stock has a $5 call and a $4 put for the post-earnings expiry. Add them — $9. The market is pricing in a swing of about 9% in either direction. Not a prediction of which way, just the size of the storm. To profit as a buyer, the real move has to beat that number after the crush takes its cut.
ATM call + ATM put ≈ the expected move. If your price target sits inside that range, the options have already priced your idea in — there is no edge left to capture.
The seller’s edge — and the train
If buyers overpay, someone on the other side gets paid. Because IV is inflated and then crushed, selling premium into earnings (say, an iron condor) profits from that deflation whenever the stock stays inside the expected move. The math tilts your way more often than not.
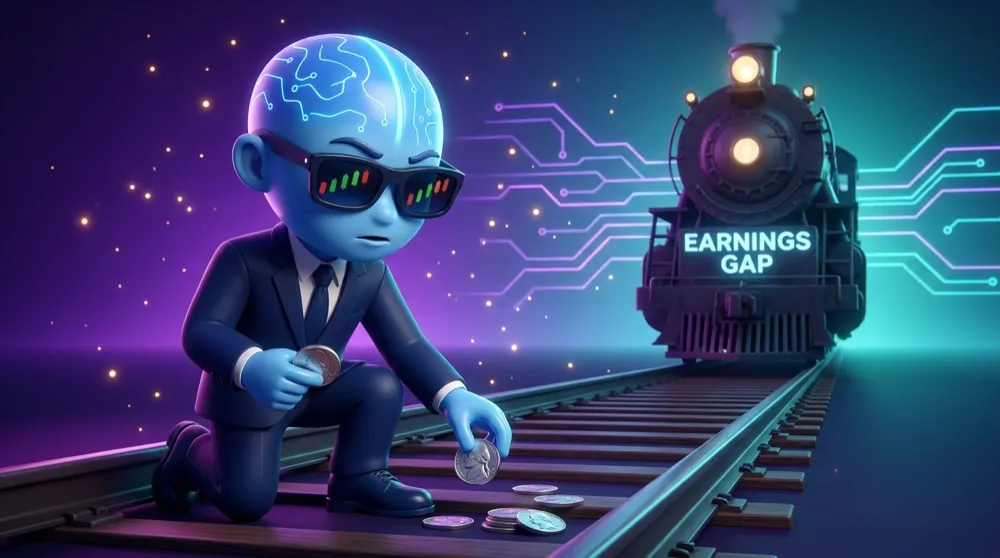
But do not fall in love with it. One blowout report can hand you a loss far bigger than the modest premium you collected. Selling into earnings is picking up nickels in front of a train — profitable most days, occasionally catastrophic. Size small, define your risk, and never bet the account on a single quarter.
The date is known; the move is not. Respect the IV crush, read the expected move before you trade, and treat earnings as a scheduled storm to plan around — not a lottery to gamble on.
You just survived your first earnings storm. Next, we slow the clock all the way down and meet options that think in years instead of days: LEAPS. 📈📉