Vega — the price of volatility
How the market's mood moves your option
Read
Your option can gain or lose money on a day the stock never moves. The culprit is the market’s mood — and Vega is the gauge that measures it.
Here’s a fact that feels illegal the first time you meet it: an option’s price can jump even when the stock stands perfectly still. How? Because options get more expensive when the market expects bigger swings, and cheaper when it expects calm.
Vega measures that reaction. It tells you how much your option’s price changes when expected volatility rises or falls by one percentage point — the market’s mood ring, priced into your position.
Own a call with Vega 0.12, and expected volatility jumps 3 points overnight with the stock flat? You gain roughly 0.12 × 3 ≈ $0.36 per share — pure mood, zero movement.
Who wins when volatility rises
Higher expected volatility means more possible outcomes, and more possible outcomes make an option worth more. That single fact splits the market into two camps:
Option buyers are long Vega — rising volatility inflates what they hold, so they secretly root for chaos. Option sellers are short Vega — rising volatility inflates what they owe, so they pray for calm. When volatility spikes, the options a seller is short get more expensive to buy back. That’s Vega working against them.
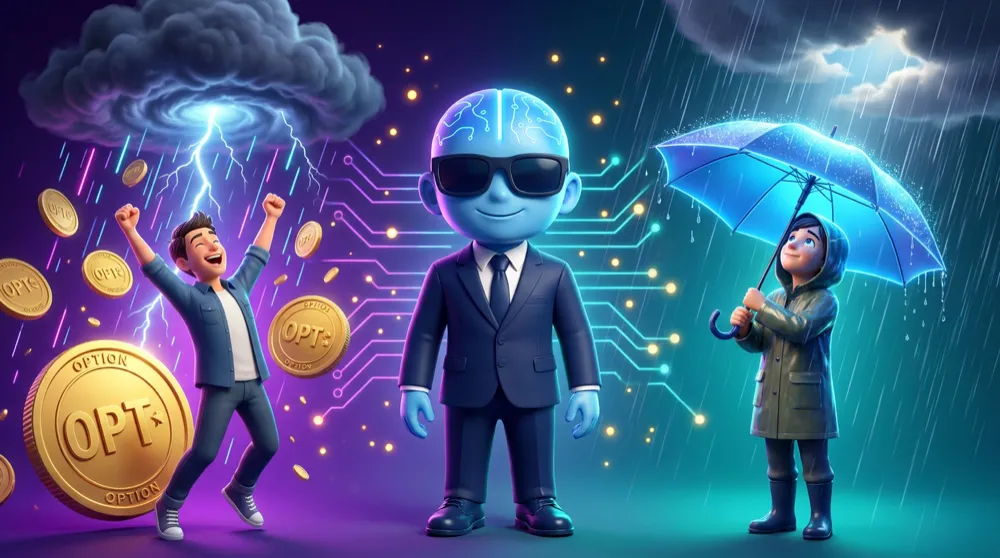
Buy options and you root for the storm. Sell them and you pray for calm.
Vega is largest for options with more time until expiration — more runway means more room for volatility to matter. As expiry nears, Vega shrinks toward nothing.
Two different bets
This is the insight that levels up your trading. Delta is a bet on direction — will the stock go up or down? Vega is a bet on turbulence — will the ride get bumpier or calmer? They’re completely separate questions.
Which means you can be dead right on direction and still lose. If the stock creeps your way but volatility collapses, Vega can drain more value than Delta adds. You called the coin flip correctly and the house still took your chips — because you were also, quietly, betting on turbulence.
Every time you buy an option you’re taking two positions at once: one on direction, one on volatility. Ignore the volatility half and it can wreck a perfectly good directional call.
So the market’s mood matters as much as its direction, and Vega is how you price it. But that raises a bigger question: this “expected volatility” number Vega reacts to — where does it even come from, and how do you tell if it’s cheap or dear? Next: Implied Volatility & IV Rank. 📈