Theta — time decay
The rent the clock charges you
Read
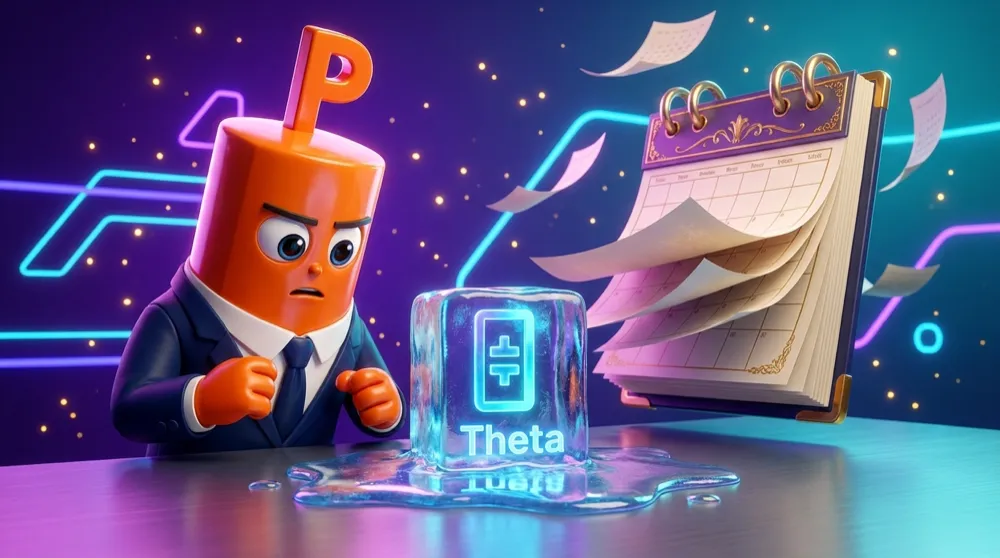
Every option is a melting ice cube. Theta is the gauge that tells you how fast it drips away — and who’s standing underneath collecting the drops.
Part of what you pay for an option is pure time value — the price of the possibility that things could still swing your way before expiration. But there’s a cruel arithmetic hiding in that word time: every day that passes, there’s a little less of it. So a little value quietly melts away.
Theta measures how much melts per day. It’s the drip, drip, drip of the clock draining your option — whether or not the stock moves an inch.
Theta of −0.08 means roughly $0.08 of value evaporates per share, per day, all else equal. On a 100-share contract that’s about $8 a day — bleeding out whether the market is open or closed.
Who pays and who collects
Theta is written as a negative number because time works against whoever owns the option. But that decay doesn’t vanish into thin air — it drips from one pocket into another:
Buyers pay Theta. Value bleeds out of what you hold every single day. Sellers collect Theta. That same decay drips into their pocket instead. And here’s the sneaky part: weekends count. The clock keeps ticking even when the market is closed, so a Friday-to-Monday hold can quietly shed three days of value.
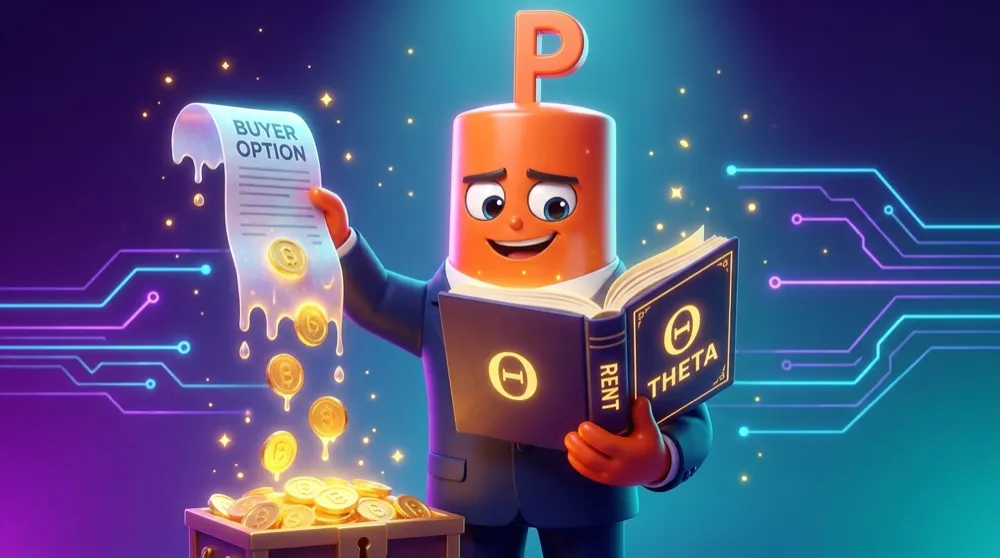
Own options and you rent time. Sell them and you become the landlord.
A seller who profits from decay is said to be long Theta — time is on their side, and every quiet day pays them. Buyers are the opposite: they need the stock to move before the clock empties their option.
Decay speeds up at the end
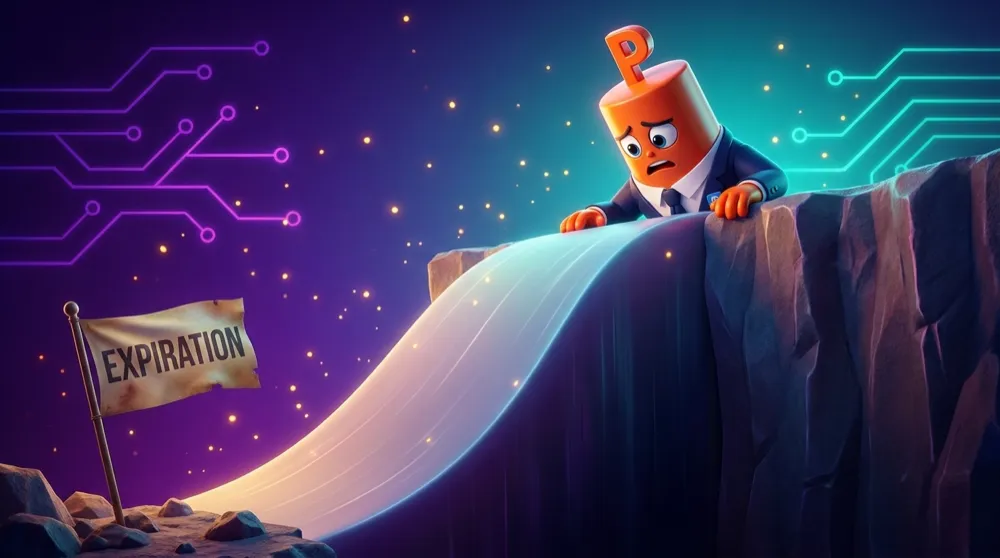
Here’s the trap that catches newcomers: time decay is not a straight line. Far from expiration it’s a slow, gentle trickle. But in the final weeks — especially for at-the-money options — it accelerates sharply, dumping value fast right before expiry.
So the intuition “I’ve got weeks left, I’m fine” is exactly backwards near the deadline. The final stretch is a cliff, not a slope. That last week is where at-the-money options shed their time value fastest — the opposite of slowing down.
A buyer can be dead right about direction and still lose if they wait too long. The stock doesn’t have to fall for you to bleed — it just has to sit still while Theta runs the clock down.
So time is never free — it’s a rent the clock charges every option holder, and it charges the most right at the end. But Theta is only one force. What if the stock stands still and the mood of the market suddenly turns nervous? Next: Vega, the price of a jittery market. 🌪️