IV Crush & earnings
How you can be right and still lose
Read
The earnings trap: you buy a call, the stock rises, and you still lose money. Here’s the invisible force that pulls it off — and how the pros dodge it.
Before a company reports earnings, nobody knows the outcome. The stock could gap up, gap down, or barely flinch — pure suspense. All that uncertainty has to be priced somewhere, so implied volatility balloons and options get expensive in the days leading up to the report.
Then the numbers hit. In a single instant the mystery vanishes — the unknown becomes known — and all that inflated volatility deflates in seconds. That sudden collapse is IV crush, and it’s the trap that catches beginners every earnings season.
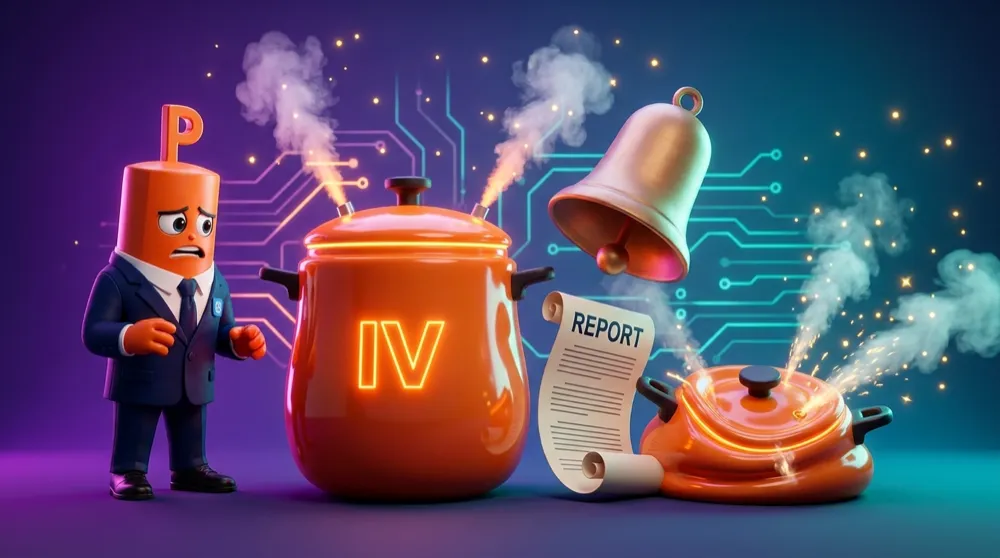
Days before earnings, IV climbs as uncertainty builds → options get expensive → earnings release → the unknown becomes known → IV collapses and option prices deflate. Predictable as clockwork.
Right direction, wrong result
Here’s the genuinely cruel part. You buy a call, the stock actually rises after earnings… and you still lose money. It feels impossible. It isn’t. It’s two Greeks pulling in opposite directions:
Delta helped you — the stock moved your way, adding value. But Vega hurt you more — IV collapsed, and as a buyer you were long Vega, so that collapse drained value fast. When the volatility loss outweighs the directional win, you’re net down despite calling the move correctly.
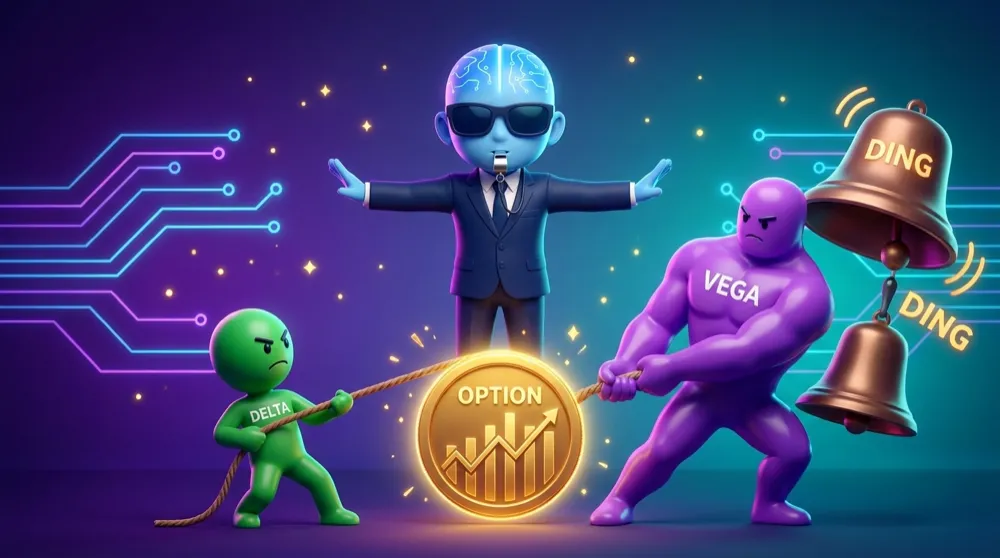
You called the direction and still lost. Vega quietly ate your gains.
Yes — you can buy a call, watch the stock climb, and lose money on IV crush. A modest up-move simply can’t outrun the value lost when inflated IV deflates all at once.
Who benefits — and how pros play it
If buyers get burned, someone must be warming their hands. That someone is the seller. Sellers are short Vega: when IV collapses after the report, the options they sold get cheaper to buy back. That decline works squarely in their favor — they pocketed the rich pre-earnings premium and watched it deflate.
You can’t avoid IV crush, but you can plan around it. To survive as a buyer, you need a move big enough to beat both the crush and the premium you paid — a high bar. That’s why many traders flip the script: they sell premium into high IV, or use spreads that cap their Vega exposure so a collapse stings far less.
Before any earnings trade, ask which side of Vega you’re on. Either sell into the inflated IV, or demand a genuinely monster move to justify buying through the crush. Never wander in blind.
And that’s the final gauge on the dashboard. You can now read Delta, Gamma, Theta and Vega, price the market’s mood with implied volatility, and sidestep the earnings trap that snags everyone else. Greeks: conquered. You’ve survived Volatility City. 🏆