Credit spreads
Get paid to open, win if nothing dramatic happens
Read
Last lesson you paid to open. Now flip it: collect cash up front, and win simply by letting nothing dramatic happen.
A debit spread makes you pay for a directional bet. A credit spread turns that upside down. You sell the closer, pricier strike and buy a cheaper, farther one for protection. Because you collect more than you spend, cash lands in your account the moment you open.
That cash is your credit — and it’s also the most you can ever make on the trade. You’re not hoping for a big move now. You’re getting paid to bet that something dramatic doesn’t happen. Very different mindset.
A debit spread pays you if you’re right about direction. A credit spread pays you just for the absence of disaster.
The protective long leg is your seatbelt
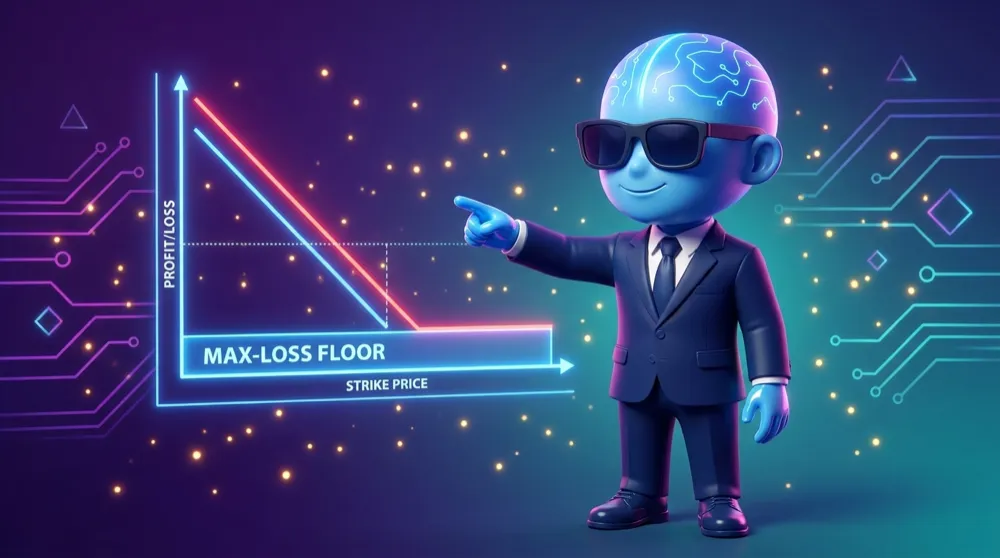
Selling an option all by itself is dangerous — a bad move can hurt you badly, with the damage running far beyond the little premium you collected. So you never sell naked up here. The extra leg you buy is a safety wall that caps how far a bad move can dig into you.
You pocket slightly less credit for that protection, but in return your risk becomes a known, fixed number instead of a terrifying open-ended “what if.” That’s a trade every sensible person makes.
A bare short option can lose far more than the credit you took in. The bought leg is what turns that open-ended danger into a defined, survivable loss. Skipping it isn’t brave — it’s how accounts get wiped out.
The bull put spread: paid to be roughly right
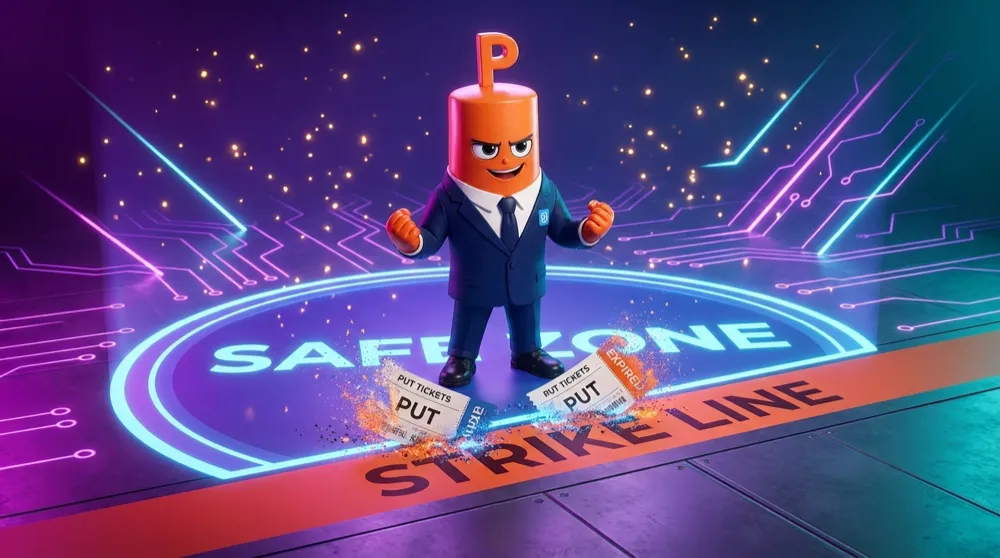
Here’s the classic. A stock sits at $100 and you think it holds above $95. You sell the $95 put and buy the $90 put for protection. You collect a credit up front. If the stock finishes anywhere above $95 at expiry, both puts expire worthless and you keep every cent.
Notice what you didn’t need: the stock didn’t have to rise. It didn’t even have to move. It just had to not crash. You get paid for being roughly right, not perfectly right — and that wider margin for error is the whole appeal.
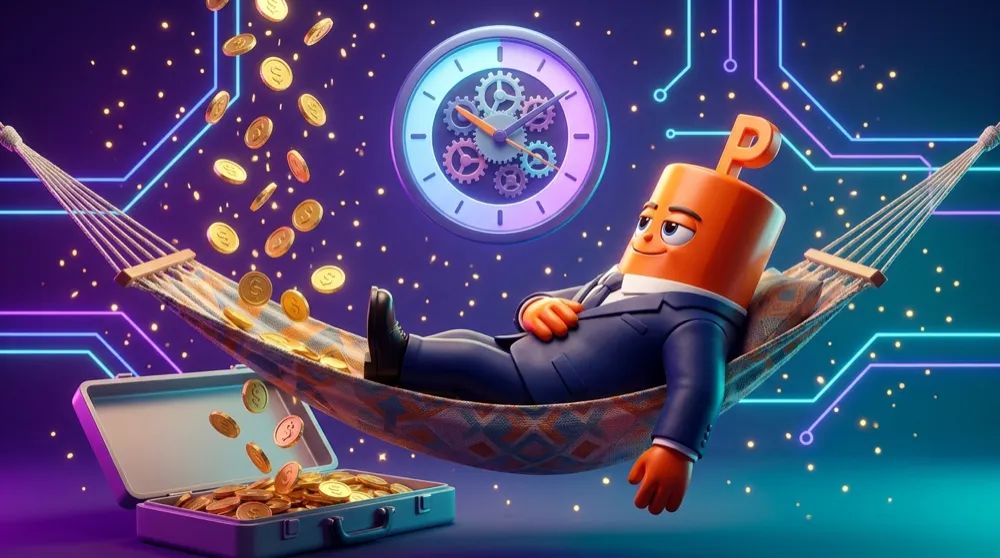
Every day, time decay quietly chips value off both options — pushing them toward worthless. When you own options, that’s your enemy. When you sell a credit spread, it’s your best friend. You literally profit from the calendar turning.
Know your worst case before you enter
Your maximum loss is easy to pin down: it’s the gap between the two strikes minus the credit you collected. Sell the $95 put, buy the $90 put, collect $1.50 → your worst case is $5 − $1.50 = $3.50 per share. That only happens if the stock falls all the way below $90, where your bought put slams the brakes.
So the shape is the mirror image of a debit spread: you take in a smaller, capped reward now, in exchange for a larger — but still capped and known — risk if things go wrong.
Collect the credit, buckle the seatbelt, and let time do the heavy lifting. That’s the credit-spread mindset. Next we’ll bolt two of these together — one above the price, one below — and get paid when the stock does absolutely nothing. 💸